Personal Finance
How to Actually Use Your HSA as an Investment Account in 2026
Sep 8, 202616 min read
By WorldFinance Editorial Team
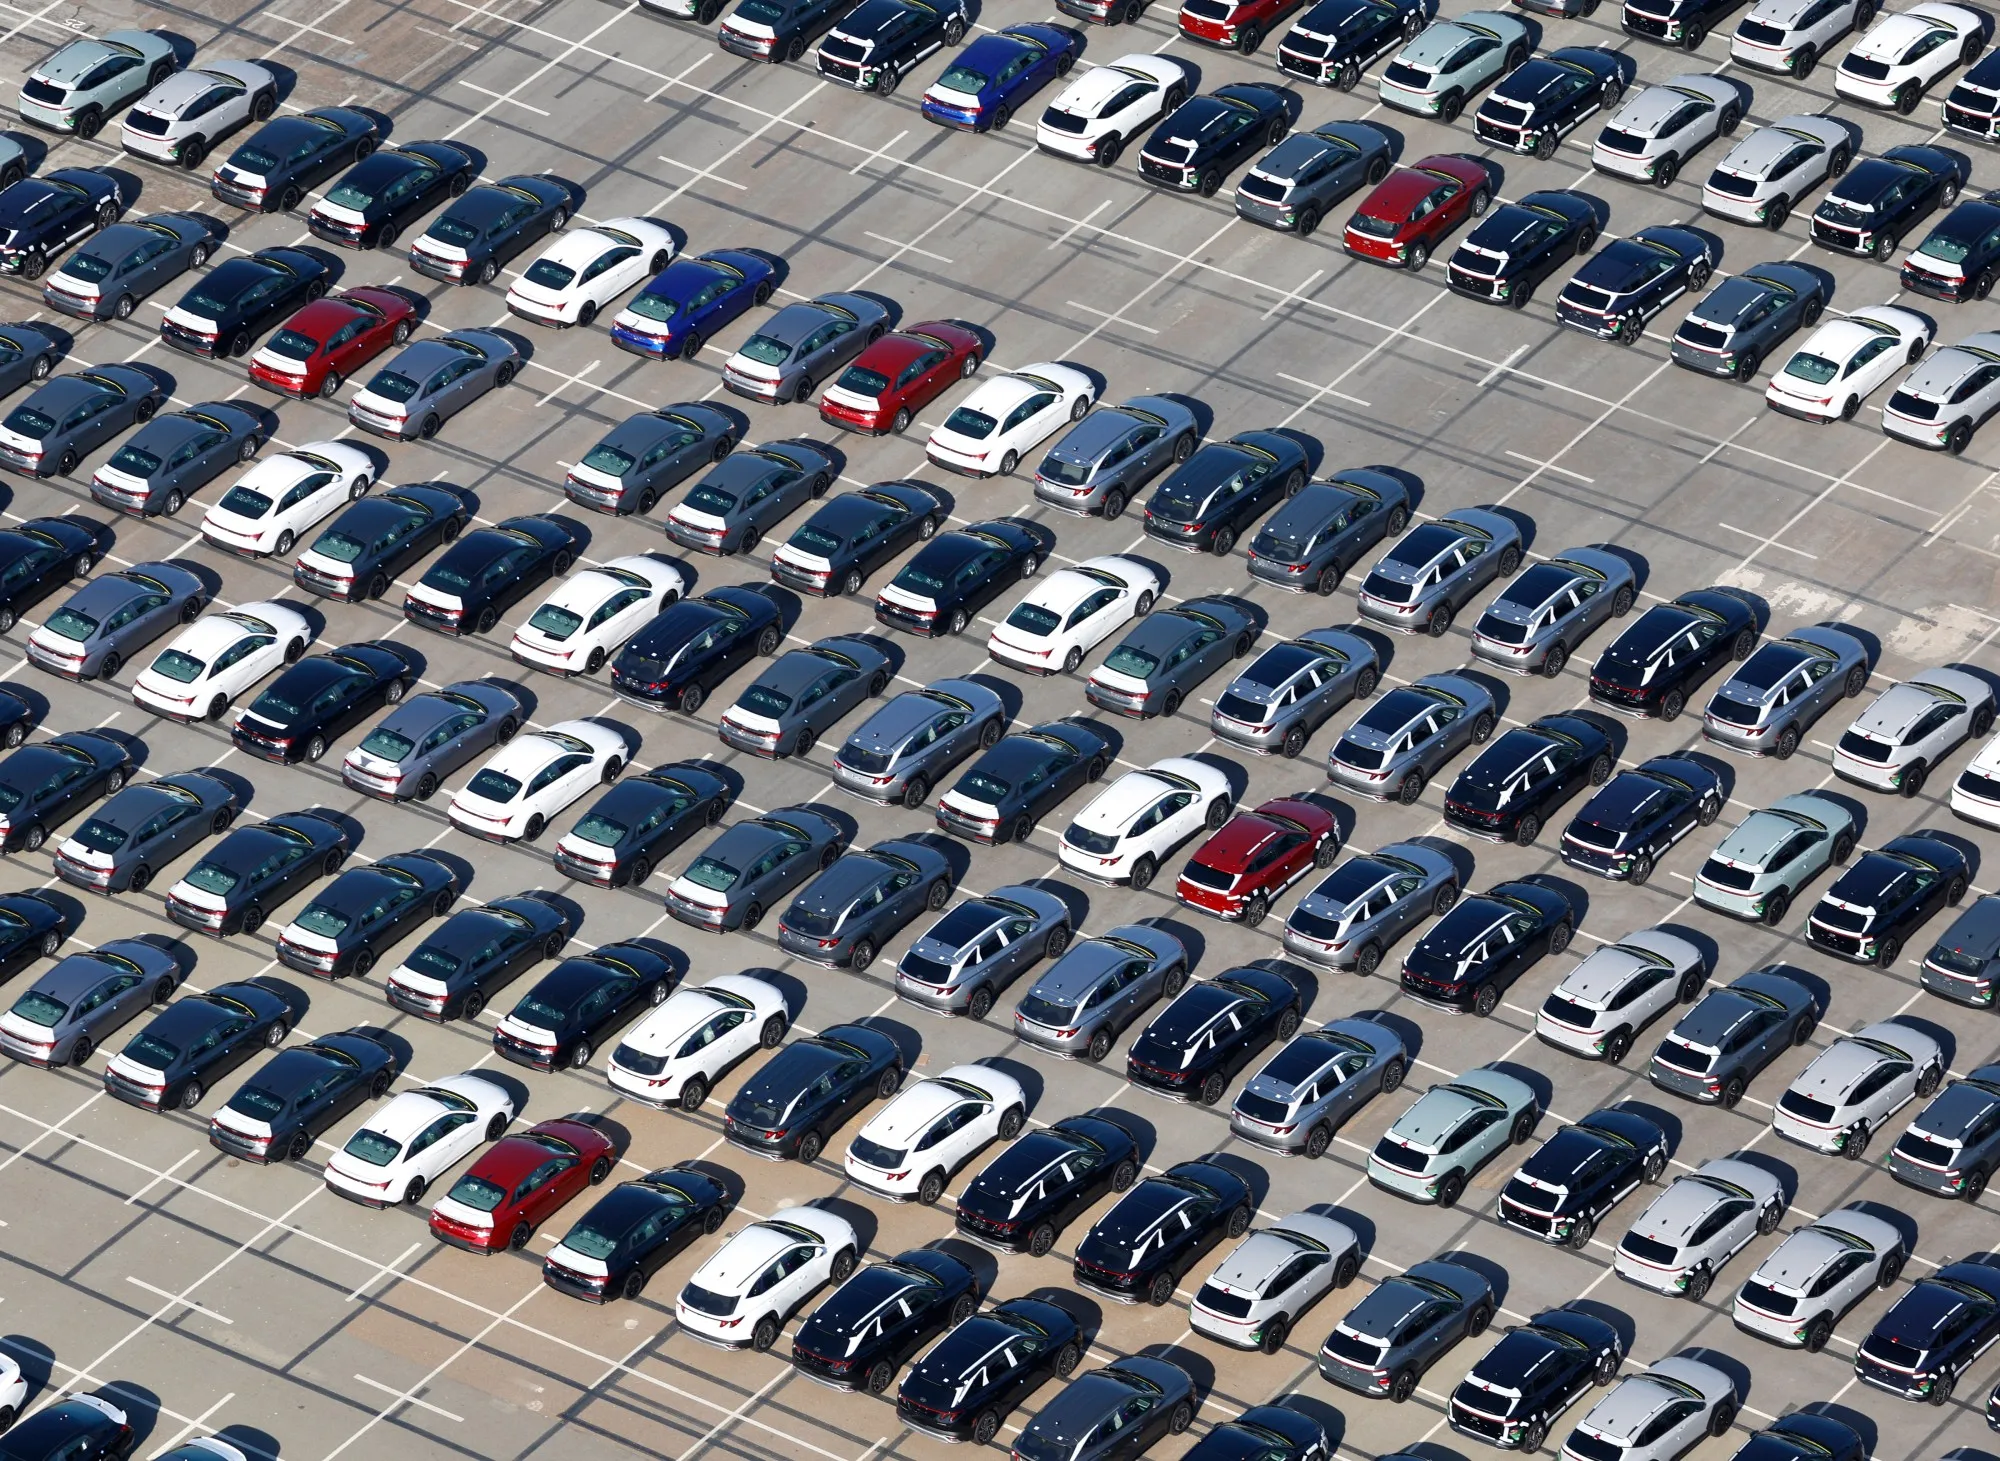
Subprime auto loan delinquencies just hit their highest level in 32 years. Nearly a quarter of new car loans now stretch to 84 months. Almost a third of trade-ins are underwater. None of that happened overnight — and none of it is slowing down yet.
Car payments have quietly become one of the clearest stress points in household budgets in 2026, and the data backs that up in a way that's hard to dismiss as noise. According to the New York Fed, 5.6% of outstanding auto debt was at least 90 days delinquent in the first quarter of 2026 — up 12.2% from a year earlier. For subprime borrowers specifically, 60-plus-day delinquencies just hit their highest level in 32 years, a record stretching back to January 1994 (CarEdge). This isn't a localized problem in one corner of the credit market. It's a broad-based stress pattern showing up across pricing, loan structure, and borrower behavior all at once.
The headline delinquency numbers understate just how unevenly this stress is distributed. Throughout 2025, subprime 60-plus-day delinquency rates ran between roughly 5.5% and 6.8%, while prime borrowers stayed in a tight band around 0.5% to 0.6% — a gap of more than tenfold between the two groups. That divergence tells you this isn't primarily a story about the broad economy tipping into crisis; it's a story about a specific segment of borrowers — those with weaker credit, thinner savings buffers, and less room to absorb rising costs — getting squeezed hard while borrowers with stronger credit profiles remain largely insulated.
That distinction matters for anyone trying to read what this data actually signals. A sharp rise in delinquencies concentrated almost entirely among subprime borrowers, while prime delinquencies stay low and stable, points toward affordability pressure hitting the most financially fragile households hardest — not a systemic credit event threatening the broader auto lending market or the financial system generally.
The affordability squeeze has several compounding causes, and none of them are new exactly — they've just accumulated. New vehicle prices are now hovering around $50,000 on average, a level that would have seemed extraordinary a decade ago. Combined with interest rates that remain elevated relative to the ultra-low-rate era many buyers financed their previous vehicle during, monthly payments have climbed accordingly: the average new-vehicle payment reached $770 in the first quarter of 2026, up 2.9% from a year earlier, while used-vehicle payments averaged $531 and lease payments averaged $619 (LendingTree).
For near-prime, subprime, and deep subprime borrowers specifically, those averages run even higher — more than $500 a month on used vehicles and more than $700 a month on new vehicles, according to industry lending data. Layer that onto wages that have lagged inflation for several consecutive years for a meaningful share of the workforce, and the math behind rising delinquencies stops looking mysterious. A borrower whose income has grown more slowly than both vehicle prices and financing costs is, almost by definition, carrying a heavier real burden than a borrower with an identical loan five years ago.
Faced with payments that don't comfortably fit standard budgets, both lenders and borrowers have leaned hard on one lever: stretching loan terms out longer. Nearly one in four new auto loans in the second quarter of 2026 carried terms of 84 months or longer — a record high for the industry. Longer terms lower the monthly payment by spreading the same loan balance over more months, which makes an otherwise unaffordable vehicle purchase appear affordable on a monthly basis, even though the buyer ends up paying meaningfully more in total interest over the life of the loan.
The connection between negative equity and term length is particularly stark. In the first quarter of 2026, 90.2% of new loans involving a trade-in with negative equity — meaning the borrower still owed more on their previous car than it was worth — carried terms of at least 72 months, and 43% stretched all the way to 84 months (J.D. Power). The average term on loans carrying rolled-over negative equity reached 77.4 months, compared with 70.3 months for new-vehicle loans overall. In practice, borrowers who are already underwater on one vehicle are systematically ending up in even longer loans on their next one — a pattern that makes escaping the cycle progressively harder rather than easier.
The scale of negative equity in the market right now is genuinely notable. In the first quarter of 2026, 30.9% of trade-ins toward new-vehicle purchases carried negative equity — the highest share of underwater trade-ins for any quarter since Q1 2021's 31.9%. The average amount owed on those underwater trade-ins reached $7,183, the second-highest quarterly level on record (Edmunds).
The financial consequences for these borrowers compound in a specific, measurable way. In the second quarter of 2026, buyers who rolled negative equity into a new loan carried an average monthly payment of $944, compared with the overall industry average of $777 — nearly $170 more per month. Their average APR also ran higher, at 7.9% compared with 6.9% for the market broadly, meaning underwater borrowers are simultaneously paying more principal, over a longer term, at a worse interest rate than the average buyer. Each of those three factors compounds the others, which is exactly why negative equity, once established, tends to persist and often deepen across successive vehicle purchases rather than resolve itself.
Understanding why negative equity is so persistent requires following the mechanics through a full purchase cycle. A borrower who's underwater on their current vehicle and needs or wants to trade it in has the negative equity rolled directly into the new loan balance, meaning they're financing not just the new vehicle's price but also the unpaid remainder of the old one. That larger balance, combined with already-elevated vehicle prices and interest rates, pushes the monthly payment higher than it would otherwise be — which is precisely the scenario that pushes borrowers toward the longer loan terms needed to bring that payment back down to something manageable.
Longer terms, in turn, slow down how quickly a borrower builds positive equity in the new vehicle, because a larger share of early payments goes toward interest rather than principal, and the vehicle itself depreciates throughout that period regardless of loan structure. That combination — slower equity buildup on a naturally depreciating asset — means a borrower who enters this cycle underwater has a meaningfully higher chance of being underwater again at their next trade-in, particularly if they trade in before the loan term is complete rather than paying it off first.
It's a fair question to ask why lenders continue extending increasingly long, increasingly large loans to borrowers who are visibly stretched thin — and the answer comes down to how auto lending risk gets priced and distributed rather than any single lender making an obviously reckless decision in isolation. Subprime auto loans carry meaningfully higher interest rates precisely because they carry meaningfully higher default risk, and much of that risk gets packaged and sold into asset-backed securities markets rather than sitting entirely on the originating lender's own balance sheet. That securitization structure spreads the risk of individual defaults across a broader pool of investors, which historically has kept the overall system functioning even when delinquencies at the individual loan level climb.
That said, rising delinquencies eventually show up in how those securitized pools get priced, and in how selective lenders become about which subprime borrowers they're willing to extend credit to going forward. Some tightening in subprime auto underwriting standards typically follows a sustained delinquency spike like the one currently playing out — lenders pull back gradually as losses accumulate, which is part of why economists watching this cycle are paying close attention to origination data in addition to delinquency data, since a meaningful pullback in subprime lending availability would be one of the clearest signs that the market is genuinely tightening in response to current stress levels rather than continuing to extend credit at the same pace regardless.
It's worth addressing directly why this cycle, despite the alarming 32-year delinquency record, isn't being widely described as a repeat of the conditions that preceded the 2008 financial crisis. The structural difference is significant: the 2008 crisis was driven substantially by mortgage lending practices and complex derivative products built on top of them, where losses cascaded through the broader financial system in ways that were difficult to contain once they began. Auto lending, even subprime auto lending, operates at a smaller absolute scale relative to the broader financial system, and the current stress is heavily concentrated in one identifiable borrower segment rather than spreading broadly across credit types and borrower profiles simultaneously.
That's a meaningful distinction, but it's not a reason for complacency about the underlying household-level pain this data represents. A delinquency or repossession is a serious financial and personal event for the individual household experiencing it, regardless of whether it poses systemic risk to the broader financial system. The absence of a 2008-style contagion risk doesn't mean the current auto loan stress is insignificant — it means the consequences are concentrated at the household level rather than threatening to cascade outward, which is precisely why understanding your own exposure and options matters more than trying to predict a broader financial system event that current data doesn't particularly support.
For anyone currently facing a car payment that's straining their budget, or considering a new vehicle purchase in this environment, a few practical steps make a real difference. First, resist the instinct to solve payment stress purely by extending the loan term further — a lower monthly payment achieved through a longer term often means paying significantly more in total interest and staying underwater longer, which can make the next purchase even harder to finance affordably.
Second, if you're currently underwater and not in a position where you need to trade in immediately, consider holding onto the vehicle longer rather than trading in while still owing more than it's worth. Every additional month of payments without rolling in a new purchase is a month spent closing the equity gap rather than deepening it. Third, if a trade-in is unavoidable, it's worth shopping the negative equity amount specifically — some dealers and lenders offer meaningfully different terms for rolling over underwater balances, and the difference between a 6.9% and 7.9% APR on a five-figure balance adds up to real money over a multi-year loan.
Finally, for borrowers already showing signs of delinquency stress, reaching out to the lender proactively before missing payments — rather than after — tends to produce far better outcomes. Many auto lenders have hardship programs, payment deferral options, or loan modification processes available to borrowers who contact them early, options that become considerably harder to access once an account has already gone seriously delinquent and moved toward repossession proceedings.
Before signing any new auto loan in this environment, it's also worth running the total-cost-of-ownership math rather than focusing exclusively on the monthly payment figure a dealer presents. A loan that looks affordable at $500 a month over 84 months can cost thousands more in total interest than a shorter loan with a higher monthly payment, and understanding that full cost — not just whether the monthly number fits the budget today — is the clearest way to avoid becoming part of next year's negative equity statistics.
The current data doesn't point toward an imminent broad-based auto lending crisis — the concentration of stress in subprime borrowers, with prime delinquencies remaining low and stable, suggests this is an affordability problem hitting a specific, financially vulnerable segment of the market rather than a systemic one. But it is a meaningful signal about the state of household budgets for a real and growing share of American consumers, and it's a trend worth watching closely, because vehicle prices, interest rates, and loan term structures don't appear likely to reverse quickly enough to meaningfully ease the pressure in the near term.
For households not yet in financial distress but considering a vehicle purchase, the clearest lesson from 2026's data is to resist financing decisions that solve today's payment problem by creating a longer, deeper version of the same problem down the road. A vehicle that requires an 84-month loan and a payment that only works because of a rolled-in negative equity balance is, almost by construction, setting up the exact conditions that are driving this year's delinquency and underwater-trade-in records in the first place. The households that come through this cycle in the strongest position will largely be the ones that treated the monthly payment as one input among several, rather than the only number that mattered when deciding what they could actually afford.
Q: How bad are auto loan delinquencies in 2026 compared to historical norms? A: Subprime 60-plus-day delinquencies just hit their highest level in 32 years, while 5.6% of total outstanding auto debt was at least 90 days delinquent in Q1 2026 — up 12.2% year-over-year. Prime borrower delinquencies, however, remain low and stable around 0.5% to 0.6%.
Q: Why are auto loan terms getting so much longer? A: Rising vehicle prices — new vehicles now average around $50,000 — combined with elevated interest rates have pushed monthly payments higher. Extending loan terms, sometimes to 84 months or longer, lowers the monthly payment even though it increases total interest paid over the life of the loan.
Q: What is negative equity on a car loan, and how common is it right now? A: Negative equity means owing more on a vehicle than it's currently worth. In Q1 2026, 30.9% of trade-ins toward new-vehicle purchases carried negative equity — the highest share since Q1 2021 — with an average underwater amount of $7,183.
Q: How much more do underwater borrowers pay compared to average buyers? A: In Q2 2026, buyers who rolled negative equity into a new loan paid an average monthly payment of $944, versus $777 industry-wide, and faced a higher average APR of 7.9% compared to 6.9% for the broader market.
Q: What should I do if I'm underwater on my car loan? A: If possible, avoid trading in while still owing more than the vehicle is worth — continuing to make payments closes the equity gap rather than deepening it. If a trade-in is unavoidable, shop the negative equity balance specifically, since financing terms for rolled-over debt vary meaningfully between lenders.
Q: What should I do if I'm at risk of missing a car payment? A: Contact your lender proactively before missing a payment rather than after. Many auto lenders offer hardship programs, payment deferrals, or loan modifications to borrowers who reach out early, and those options become significantly harder to access once an account is already seriously delinquent.