Personal Finance
The 2026 Auto Loan Delinquency Spike: What Rising Car Payments Mean for Household Budgets
Sep 18, 202613 min read
By WorldFinance Editorial Team
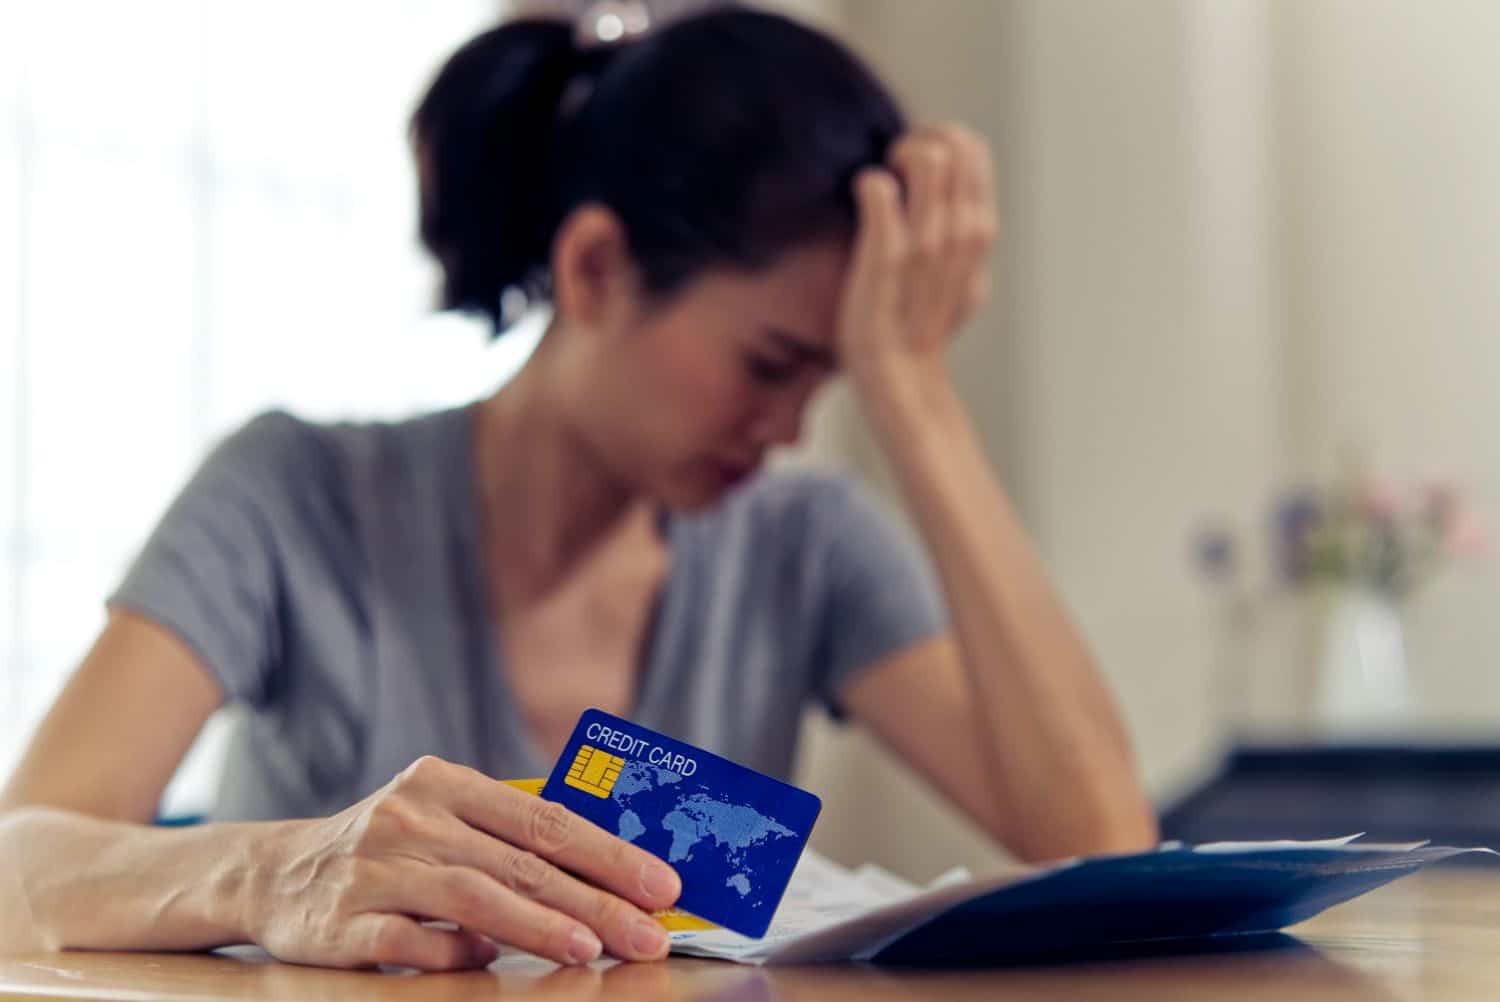
US credit card debt hit $1.263 trillion in Q2 2026, just below the all-time record, with average APRs running 21-25%. Here's a real strategy to pay it down.
American credit card balances hit $1.263 trillion in the second quarter of 2026, according to the Federal Reserve Bank of New York — just shy of the all-time record of $1.28 trillion set in the fourth quarter of 2025 (CNBC). Credit card debt now makes up about 6.7% of all household debt in the US. Per-household figures vary by methodology, but WalletHub puts the average balance at roughly $11,153 as of early 2026 (WalletHub) — a substantial amount to be carrying at today's interest rates.
Credit card debt is always expensive, but the math is especially unforgiving at current rates. Average credit card APRs have been running in the 21-25% range through 2026 (Forbes Advisor), meaning a household carrying the average balance could be paying well over $2,000 a year in interest alone before making any progress on the principal. That's the core reason financial advisors treat high-interest credit card debt as a priority above nearly every other financial goal, including investing — no reliable investment consistently outperforms a guaranteed 20%+ "return" from eliminating that debt.
A few forces reliably drive balances higher: the ease of contactless and one-click online payments that make spending feel abstract, the pull of rewards programs and sign-up bonuses that encourage more card use, and — increasingly — the use of credit cards to cover essential expenses like groceries and rent rather than purely discretionary purchases when budgets get tight. Once a balance exists, high APRs compound it further, especially for anyone making only minimum payments, which can stretch payoff timelines out for years and multiply the total interest paid many times over.
Making only the minimum payment is one of the most expensive mistakes a cardholder can make. Minimum payments are typically calculated to cover interest plus a small sliver of principal, which means a balance can take a decade or more to pay off — and cost multiples of the original amount in interest — if nothing beyond the minimum is ever paid.
Two well-established payoff methods work for different psychological styles:
Beyond picking a method, a few additional levers can help: consolidating multiple balances into a single lower-rate personal loan or balance-transfer card can simplify payments and cut interest costs; calling your card issuer to ask for a lower rate or a fee waiver sometimes works, especially for customers with a solid payment history; and building even a basic budget that tracks income against expenses makes it much easier to find extra dollars to put toward payoff each month.
Carrying a high balance relative to your credit limit — your credit utilization ratio — is one of the biggest factors in your credit score, which means heavy card debt can make it harder and more expensive to qualify for a mortgage, auto loan, or even a lower-rate balance-transfer card later. Beyond the numbers, the stress of carrying significant debt is a well-documented source of anxiety that can affect everything from sleep to relationships, which is its own reason to prioritize getting the balance down.
For anyone feeling overwhelmed by multiple balances or unsure where to start, nonprofit credit counseling agencies can build a structured payoff plan, negotiate with creditors on your behalf, and provide ongoing budgeting support — often at low or no cost through accredited nonprofit organizations.
How much credit card debt does the average American household carry? Estimates vary by methodology, but recent 2026 data puts the average household balance in the range of $6,600 to $11,150, depending on the source and whether households without any card debt are included.
How much total credit card debt does the US have? $1.263 trillion as of Q2 2026, according to the Federal Reserve Bank of New York — just below the all-time record of $1.28 trillion set in Q4 2025.
What's the best way to pay off credit card debt? The avalanche method (highest interest rate first) minimizes total interest paid; the snowball method (smallest balance first) can be more motivating psychologically. Either beats making only minimum payments.
Why are minimum payments such a bad idea? Minimum payments are calculated to cover interest plus a small amount of principal, which can stretch payoff timelines to a decade or more and multiply total interest paid several times over.
Can I negotiate a lower interest rate with my credit card company? Yes, it's often worth asking, particularly if you have a solid payment history — issuers sometimes offer a lower rate or a temporary hardship program rather than risk losing a customer to a competitor.
Is credit counseling worth it? For anyone with multiple balances or feeling overwhelmed, accredited nonprofit credit counseling agencies can provide a structured plan and creditor negotiation, often at low or no cost.