Real Estate
Insurance-Driven Relocation: How 2026 Homeowners' Insurance Costs Are Reshaping Migration to the Midwest
Sep 18, 202613 min read
By WorldFinance Editorial Team
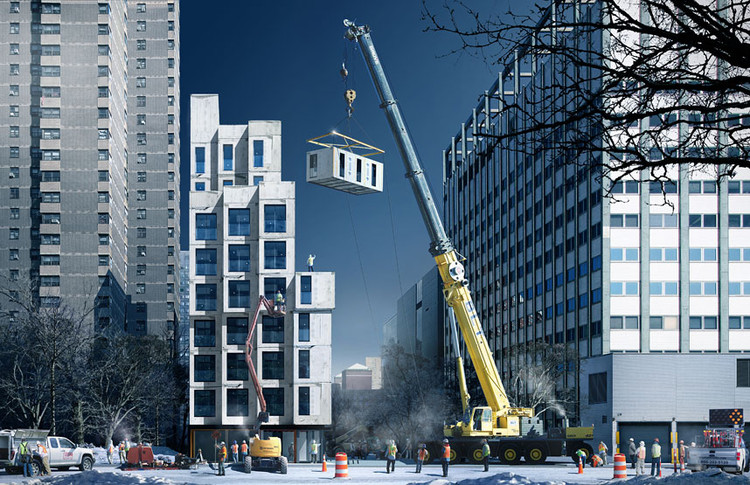
Co-living is a genuine growth market heading toward $16-28 billion by 2030, with London's real regulatory framework offering a model for how cities are balancing density with affordability.
Co-living — purpose-built shared housing with private bedrooms and communal kitchens, lounges, and coworking space — has grown from a niche experiment into a genuine real estate category. Market forecasts vary by methodology, but most converge on roughly $16 billion to $28 billion in global market size by 2030, up from around $7.8 billion in 2024, reflecting a compound annual growth rate in the 12-15% range (Grand View Research; Market.us). The growth is being driven by genuine forces: urbanization, evolving work patterns, and intensifying pressure on housing affordability in major cities.
London offers the clearest example of a city building explicit rules for this asset class. The London Plan's guidance for "Large-Scale Purpose-Built Shared Living" — what's commonly called co-living — applies to developments of roughly 50 units or more and sets specific requirements developers must meet (Greater London Authority). The policy requires developments to provide an affordable housing contribution equivalent to 35% of residential units at a 50% discount to market rent, mandates well-ventilated, flexibly designed communal areas to foster genuine community interaction, and sets a minimum tenancy length of three months specifically to prevent these developments from functioning as unlicensed hostels.
That framework matters as a model because it addresses the two biggest regulatory tensions in co-living directly: ensuring genuine affordability contribution rather than just marketing shared space as a workaround for smaller, cheaper units, and setting minimum lease lengths that distinguish co-living from short-term hospitality uses that would require different licensing.
For residents, co-living bundles furnished private space with amenities and social infrastructure that would be expensive or impractical to arrange independently — on-site management, flexible lease terms, and built-in community programming appeal particularly to younger professionals and people relocating to a new city for work. For operators, the model can generate premium revenue per square foot compared to conventional rentals, since tenants are often willing to pay more for the bundled amenities and flexibility, while shorter, more flexible lease structures can support high occupancy even as individual tenants turn over more frequently than in traditional rentals.
City governments face a genuine balancing act with co-living. On one hand, it can help address housing shortages for younger workers and address underused office or hotel-adjacent real estate through adaptive reuse. On the other, regulators have to guard against operators using "shared living" classifications to sidestep normal affordable housing requirements, minimum unit size standards, or fire and safety rules that apply to conventional multifamily housing. London's approach — requiring a genuine affordable housing contribution and minimum tenancy lengths as a condition of the more flexible density allowances — reflects how cities are trying to capture co-living's benefits while closing the most obvious loopholes.
Real risks and considerations for anyone evaluating co-living as an investment category:
How big is the global co-living market expected to be by 2030? Estimates vary by research firm and methodology, but most fall in the range of $16 billion to $28 billion, up from roughly $7.8 billion in 2024.
What does London's co-living policy actually require? Developments of roughly 50+ units must provide an affordable housing contribution equal to 35% of units at a 50% rent discount, include genuinely usable communal space, and set minimum three-month tenancies to prevent the format from functioning as an unlicensed hostel.
How does co-living differ from a traditional shared apartment? Co-living operators provide furnished private rooms, professionally managed communal amenities, on-site staff, and app-based management — a more service-oriented model than unrelated roommates independently renting and managing a unit together.
What's the biggest regulatory risk for co-living investors? Policy uncertainty — many cities still treat co-living in a zoning gray area without explicit rules, meaning a future tightening of fire-safety, density, or affordable-housing requirements could force costly retrofits.
Is co-living considered affordable housing? Generally not by default — most cities treat it as a distinct use category, though policies like London's require developers to include a genuine affordable-housing contribution as a condition of the added density flexibility.
Where does co-living work best as a business model? In markets with high conventional rental costs and a large population of mobile younger renters or professionals — it's a weaker fit in cities with abundant, affordable conventional rental supply.